

MoBill Budget and Reminder
MoBill Apps
- 4.0
- 1.56K Reviews
- 500.00K
- Downloads
- Free
- Price
Screenshots
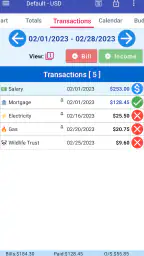
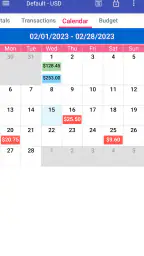
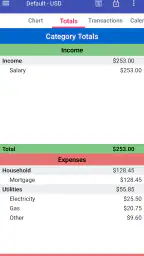
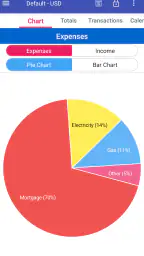
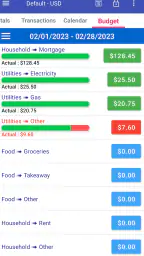
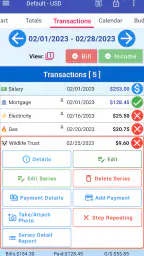
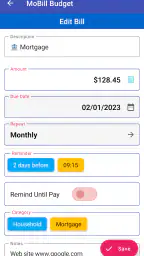
MoBill Budget and Reminder Pros and Cons
Pros
- Simple budgeting tools for tracking income and everyday expenses.
- Bill reminders help reduce the risk of missing recurring payments.
- Useful overview of upcoming financial obligations in one place.
- Lightweight design makes the app quick to open and navigate.
- Can support better spending awareness without requiring complex setup.
Cons
- Some advanced budgeting features may require a paid upgrade.
- Manual expense entry can become time-consuming for frequent transactions.
- Reminder reliability may depend on notification and battery settings.
- Limited integrations could make automatic bank tracking unavailable.
- The interface may feel basic for users wanting detailed financial reports.
 Analysis by All-app
Managing bills is rarely difficult because of one large payment. The real problem is the collection of small due dates, changing amounts, forgotten renewals, and everyday spending that quietly pushes a budget off course. MoBill Budget and Reminder approaches that problem by putting personal budgeting and bill reminders in the same finance app. After using it, I see its main value less as a full financial dashboard and more as a practical routine: record what needs to be paid, give it a place in your budget, and use reminders to reduce the chance of overlooking it.
That focus makes the app easy to understand. It is free to download, developed by MoBill Apps, and suitable for everyone. It has been available since February 28, 2011, and the current version is 5.3.1. With more than 500 thousand installs and an average rating of 4.0 from roughly 3.8 thousand ratings, it has clearly found a steady audience among people looking for a straightforward way to keep household finances under control.
Why the bill-reminder capability matters more than it first appears
The most useful idea here is the connection between a bill and the budget around it. A reminder by itself can tell me that a payment is approaching, but it does not necessarily show what that payment does to the rest of the month. A budget by itself can show planned spending, but it does not help much if I forget the payment date. Combining the two creates a more useful question: “Can I afford this bill when it is due?”
That question is especially important for expenses that do not feel urgent every day. Rent, utilities, insurance, school costs, memberships, and annual renewals can sit in the background until the payment date is close. When they are recorded early, I can treat them as commitments rather than surprises. That changes the way I look at the money left in my account. Instead of considering the full balance available, I can mentally reserve the amount needed for upcoming obligations.
In my experience, this is where the app has a practical advantage over a basic notes application. A note can contain a list of due dates, but it usually leaves the user to interpret the list manually. MoBill Budget and Reminder is built around the financial meaning of those entries, so the reminder is not isolated from the budgeting task. The real benefit is not simply remembering a bill; it is making the bill visible before it becomes a problem.
This also makes the app different from a bank application. A bank app is useful for checking completed transactions and current balances, but it may not encourage me to plan for a payment that has not happened yet. MoBill Budget and Reminder is more forward-looking. It asks me to think about intended payments and spending decisions before the account balance gives me a reason to react.
Turning recurring obligations into a routine
The strongest use case is a household with several regular payments arriving at different times. Even when the amounts are familiar, the dates may not be. One bill may be due near the beginning of the month, another in the middle, and another shortly afterward. The app gives those obligations a consistent place, which is more useful than relying on memory or scattered calendar entries.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
I would begin by entering the bills that would cause the most trouble if missed. That might include housing, utilities, insurance, or a payment connected to work or transportation. Once those are visible, I would add less urgent recurring expenses. This order matters because it prevents the budget from becoming a long, intimidating list before the essentials are covered.
A good habit is to review the upcoming obligations at the same time each week rather than waiting for a reminder to appear. The reminder then becomes a safety net, not the entire system. I can check what is approaching, compare it with the money I expect to have available, and decide whether discretionary purchases need to wait. This workflow is more reliable than opening a finance app only after a payment has already been missed.
There is also a useful psychological effect. When a bill is recorded, it stops being an invisible future problem. I can see it as part of the month’s plan. That does not reduce the amount owed, of course, but it reduces the chance that I will accidentally spend money that was already committed. For people whose main budgeting difficulty is timing rather than mathematics, that distinction is important.
A realistic month with uneven income
Imagine someone paid near the end of the month who also has several expenses due during the first two weeks of the next month. Without planning, the account may look healthy immediately after payday. A few ordinary purchases can then consume money that is actually needed for upcoming bills. When the reminders arrive, the user is forced to catch up.
With MoBill Budget and Reminder, the user can review those early-month obligations while the balance is still available. The budget becomes a warning against treating the whole balance as spending money. If income varies, the app is even more useful as a planning aid, although it still depends on the user entering realistic amounts and checking the plan regularly. It cannot make an unpredictable income predictable; it can only make the commitments easier to see.
For a couple or family, the same routine can help expose responsibilities that are otherwise assumed rather than discussed. One person may remember the utility payment while the other remembers the insurance renewal. Keeping the obligations together gives both people a clearer starting point for a conversation about what must be paid and what can be postponed.
Where the app fits among everyday alternatives
A paper planner is flexible and reassuringly simple, but it requires manual checking and does not naturally connect due dates with a spending plan. A calendar is excellent for appointments and time-based alerts, yet it is not designed around the difference between income, fixed obligations, and available spending. A spreadsheet can offer more control, but it takes more effort to build and maintain, especially on a phone.
MoBill Budget and Reminder sits between those options. It is more focused than a calendar and less demanding than a custom spreadsheet. Compared with a dedicated banking tool, it is better suited to planning expenses before they leave the account. Compared with a full-featured financial platform, its appeal is likely to be its narrower purpose: bills and budget control without requiring me to turn every financial decision into a complicated reporting project.
That middle position is both its strength and its limitation. If I want advanced investment tracking, detailed account synchronization, tax preparation, or a broad household finance dashboard, I would look elsewhere. If I mainly need a dependable place to organize bills and keep spending intentions visible, the simpler approach is more attractive.
Using the app without making budgeting exhausting
The first setup should be deliberate rather than rushed. I would not try to enter every minor purchase immediately. I would start with income, essential recurring bills, and the budget categories that regularly cause trouble. This creates a useful baseline and makes it easier to notice whether the app is helping. Adding too much detail at once can turn a helpful reminder system into another chore.
For variable bills, I would use an amount that is realistic for planning rather than relying on an unusually low month. The purpose is not to make the budget look comfortable; it is to avoid being surprised. When the actual amount is known, I would adjust the record and treat the difference as information for the next planning cycle. This is one of the more important trade-offs in any manual budgeting tool: the quality of the result depends on the quality and regularity of the entries.
I also recommend separating essential bills from optional recurring charges in my own thinking, even if both appear in the same overall financial picture. A subscription that can be canceled should not receive the same priority as housing or electricity. That distinction makes the reminders more actionable. When the budget is tight, I know which items require payment and which items deserve review.
Another useful workflow is to check the app before making a larger nonessential purchase. I would look at the next group of reminders first, then ask whether the purchase still fits after those obligations are mentally reserved. This takes only a moment, but it prevents the common mistake of judging affordability from the current balance alone.
What the current version means for new users
The current version is 5.3.1, and the app requires Android 8.0 or later. That makes the operating-system requirement worth checking before installation, particularly on an older phone. For someone using a supported device, the app is positioned as an accessible finance tool rather than a specialist product.
The free price makes it easy to try without committing money first. There are in-app purchases ranging from $2.50 to $10.99 per item, so I would pay attention to which functions are included in the free experience and which may require an optional purchase before building a long-term routine around it. The important practical point is that the app can be evaluated on a real month of bills before deciding whether any paid addition is worthwhile.
Because the content rating is Everyone, it is suitable for a broad audience. That does not mean every user will find it equally useful. A teenager learning to track a small allowance may find a simpler note or spreadsheet sufficient, while an adult managing several due dates may appreciate the dedicated structure. The app’s usefulness grows with the number of obligations that need regular attention.
Where friction can appear
Manual finance management always asks for discipline. If I forget to update an amount, fail to record a new bill, or ignore the upcoming list, the app cannot correct the plan by itself. This is not a flaw unique to this product, but it is important because a reminder can create false confidence. Seeing an entry on screen is not the same as knowing the payment was made or that the amount is still accurate.
There is also a possible tension between simplicity and detail. Users who want to examine every purchase may find a focused bill-and-budget workflow less satisfying than a more comprehensive finance service. On the other hand, users who have abandoned complicated budgeting tools may prefer this narrower scope because it keeps attention on the obligations that matter most.
I would also avoid treating the app as a replacement for checking the actual bank account. The app can support planning, but the bank remains the place to confirm available funds and completed payments. Using both together is safer than expecting a budget record to reflect every financial change automatically.
The rating of 4.0 from around 3.8 thousand ratings suggests a generally positive but not universally perfect experience. That feels consistent with the app’s position: it can be genuinely helpful for people who want organized reminders, while users expecting a highly automated or all-in-one financial platform may find it limited.
Who gets the most value from this approach
I would recommend MoBill Budget and Reminder to someone who repeatedly remembers bills at the last minute, spends too freely after payday, or wants a simple way to see upcoming obligations before making everyday purchases. It is particularly suitable for people who prefer entering their own information instead of handing all financial activity to an automated service.
It can also work well for someone starting a budgeting habit. The bill-reminder angle gives the routine a clear purpose. Rather than trying to analyze every spending pattern from the first day, the user can begin by protecting essential payments. Once that becomes comfortable, they can expand the budget with more categories and more detailed tracking.
I would be less likely to recommend it to someone who needs automatic transaction imports, shared real-time account management, investment tools, or sophisticated reports. A spreadsheet or a broader personal finance platform may be a better choice in those cases. I would also hesitate if the user dislikes manual entry entirely, because the app’s value depends on keeping its information current.
For me, the best way to judge it is to use it as a short weekly checkpoint. I would enter the bills that matter, review the next payments, compare them with the planned budget, and update anything that changed. That is enough to test its central capability without turning money management into a daily obsession.
My final take on the reminder-first design
MoBill Budget and Reminder succeeds when the problem is not a lack of financial information but a lack of timely attention. Its most convincing capability is the way bill reminders can support budget decisions before payments become urgent. That makes it more purposeful than a simple list and less overwhelming than many complete financial management systems.
The trade-off is clear: I get a focused planning tool, not an automatic financial command center. I need to enter accurate information, review it consistently, and confirm real transactions elsewhere. For the right user, those are reasonable requirements because they keep the system understandable and under personal control.
As a free finance app from MoBill Apps, with over 500 thousand installs and a Everyone rating, it is easy to consider for ordinary household planning. I would start with the essential bills, use the reminders as prompts for a weekly review, and avoid adding unnecessary detail until the basic routine feels useful. If your main goal is to stop upcoming payments from disappearing into the background, this is a practical app to try. If you need deep automation or advanced financial analysis, another category of tool will serve you better.
Frequently Asked Questions
What is MoBill Budget and Reminder used for?
MoBill Budget and Reminder is designed to help you organize personal finances by tracking bills, recurring payments, budgets, and due dates in one place. After setting up your regular expenses, you can use the app to monitor upcoming obligations, review payment history, and keep a clearer view of how much money is committed each month. It is primarily a planning and reminder tool rather than a banking application.
Can MoBill Budget and Reminder remind me when bills are due?
Yes, reminders are one of the app’s main purposes. You can generally create recurring bills, assign due dates, and configure notifications so that upcoming payments are less likely to be forgotten. The usefulness of these alerts depends on granting the required notification permissions and allowing the app to operate correctly in the background. It is still wise to confirm important payments independently, especially when a missed deadline could result in fees.
Does MoBill Budget and Reminder connect directly to my bank account?
MoBill Budget and Reminder should not be treated as a full bank-account synchronization service unless the specific version available on your device clearly lists that feature. Its core workflow is based on entering and managing financial information within the app. This can provide more control and privacy, but it also means that balances and transactions may need to be updated manually. Always review the app’s current permissions and store description before entering sensitive information.
Is MoBill Budget and Reminder free to download and use?
Availability, pricing, advertisements, and premium features can vary depending on the platform and the version published in your region. Before downloading, check the Google Play Store or Apple App Store listing for details about in-app purchases, subscriptions, and any limitations in the free edition. A free download does not always mean every budgeting or reminder feature is included, so reviewing the pricing section first can help avoid unexpected charges.
Is MoBill Budget and Reminder safe for managing personal financial information?
The app can be useful for organizing financial details, but you should still use sensible privacy precautions. Avoid storing unnecessary account passwords, card security codes, or other highly sensitive credentials unless the official documentation explicitly confirms secure handling. Review requested permissions, read the developer’s privacy policy, and protect your phone with a passcode or biometric lock. Because manually entered data may be important, regular backups or exports are also recommended when supported.


